
NCBA Bank Uganda is giving up part of its transaction-fee income in a push to make digital banking cheaper and attract more customers to its online channels as households and businesses face rising operating costs.
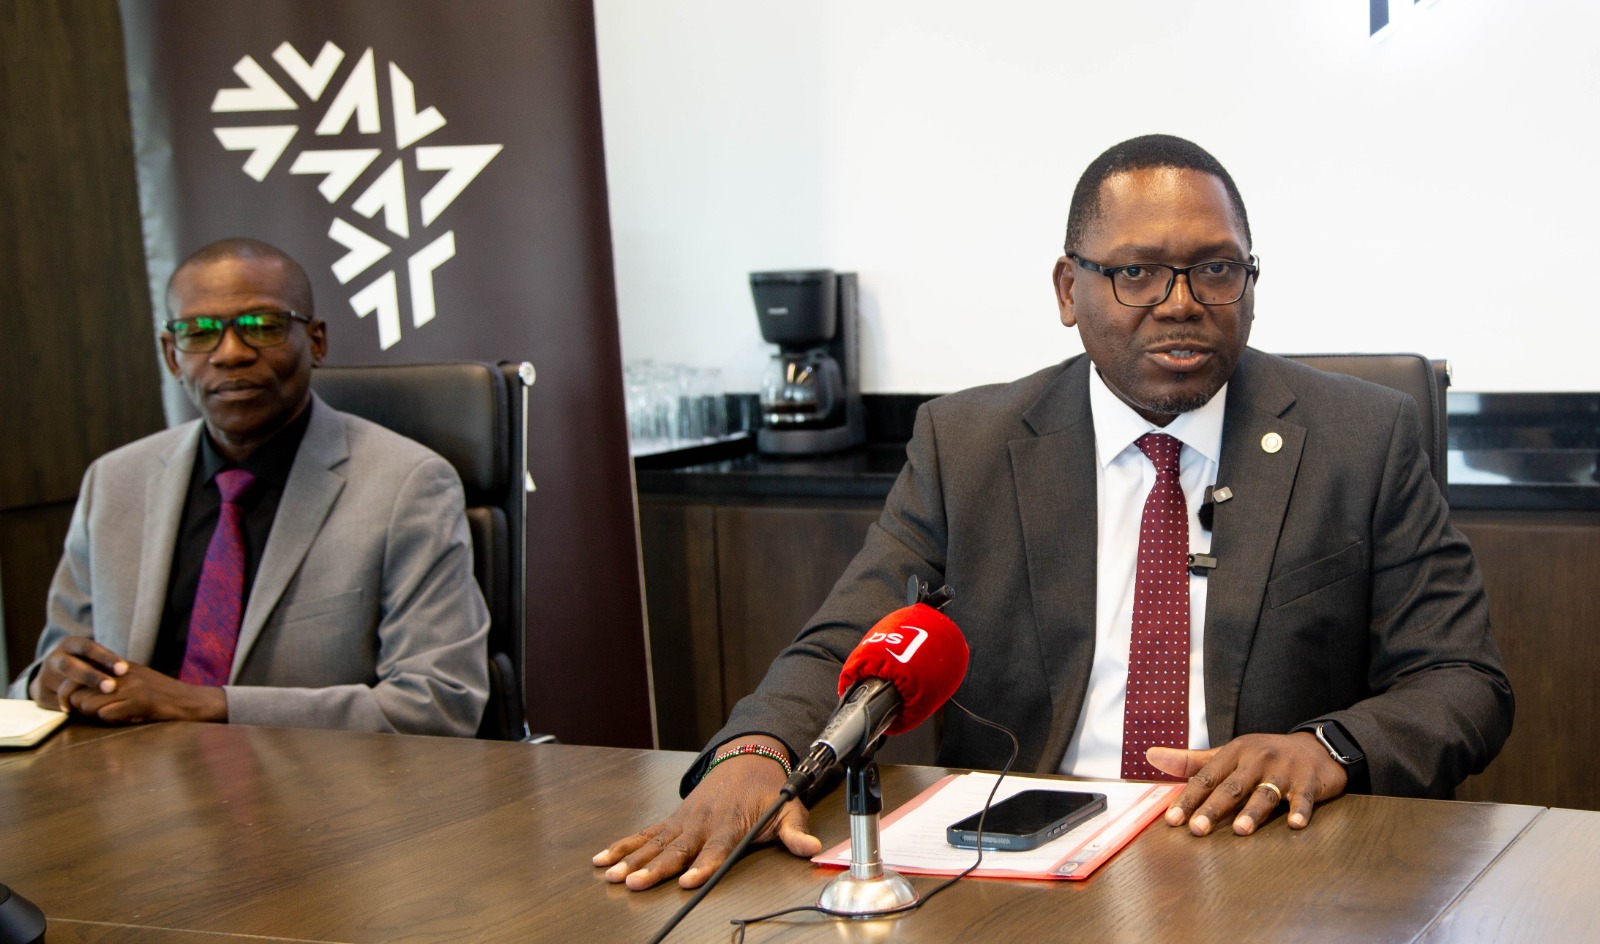
The bank has launched the NCBA NOW Zero Transaction Fees campaign, waiving fees on selected digital transactions until December 31, 2026.
The promotion, launched on October 13 at the bank’s headquarters at Twed Towers in Kampala, covers eligible transactions made through the NCBA NOW mobile application, internet banking and the *212# USSD platform.
The offer includes selected utility bill payments, bank-to-wallet transfers, Electronic Funds Transfers (EFT), Real-Time Gross Settlement (RTGS), international transfers and National Social Security Fund payments.
However, the waiver does not apply to every digital banking service, with customers required to check the applicable terms and conditions and any other charges that may remain.
The campaign represents a commercial trade-off for the lender. While removing fees could reduce income from individual transactions in the short term, NCBA is betting that lower costs will encourage customers to transact more frequently through its digital platforms and keep inactive customers engaged.
NCBA Bank Uganda Chief Executive Officer Mark Muyobo said the bank was prepared to forgo some revenue to provide relief to customers.
“There is an impact on revenue. It is not about the financial gain, but something we are willing to forfeit on behalf of the customer so that we move with them through this tough period,” Muyobo said.
The decision comes at a time when fuel prices and other operating costs are putting pressure on household budgets and business cash flows.
Muyobo said the initiative was intended to make banking more affordable while allowing customers to continue using services remotely.
The bank is also seeking to use the promotion to increase digital activity among existing customers, bring inactive customers back onto its platforms and attract people who may be looking for lower-cost banking services.
Competing for digital customers
The move reflects a broader shift in banking, where lenders are increasingly encouraging customers to conduct routine transactions through mobile and online channels rather than branches.
For banks, digital transactions can reduce some of the costs associated with serving customers through physical outlets, while giving customers access to services at any time.
But the strategy also creates a longer-term question for lenders: whether lower or zero transaction fees can generate enough additional customer activity to compensate for revenue lost from individual transactions.
For NCBA, the campaign provides an opportunity to test that balance over the remainder of the year.
The bank’s digital platforms allow customers to make payments and transfers without physically visiting a branch. NCBA’s *212# service also provides access to mobile banking for customers using phones without internet access.
The bank’s latest move also fits into its broader strategy of expanding digitally driven banking. In its 2025 integrated report, NCBA said its 2026-2030 strategy includes scaling up digitally driven capabilities and growing its personal and business banking segments.
SMEs also targeted
The digital campaign comes alongside NCBA’s existing “Ku NCBA Kiggwa Ku Bwerere” initiative targeting small and medium-sized enterprises.
Under that programme, qualifying businesses can access zero transaction fees and zero arrangement fees on selected facilities, including business loans, invoice discounting, Local Purchase Order financing and asset financing.
The SME initiative is aimed at helping businesses manage working capital and reduce some of the costs associated with accessing banking services.
For smaller businesses operating on tight margins, even relatively modest transaction or arrangement charges can add to operating costs when payments, collections and financing are frequent.
However, the fee waivers do not mean borrowing is free. Businesses taking loans will still be subject to applicable interest rates, repayment periods and other terms attached to the facilities.
Together, the two campaigns place affordability at the centre of NCBA’s current customer strategy—targeting individuals through cheaper digital transactions and businesses through selected financing and transaction-cost waivers.
The effectiveness of the digital campaign will ultimately depend on whether customers continue using the platforms after the promotion ends.
For now, NCBA is betting that sacrificing some fee income can translate into higher digital activity, stronger customer retention and a wider customer base by the end of the year.




Leave a Reply